Dubai vs London vs Singapore: Where Should You Invest in Property?
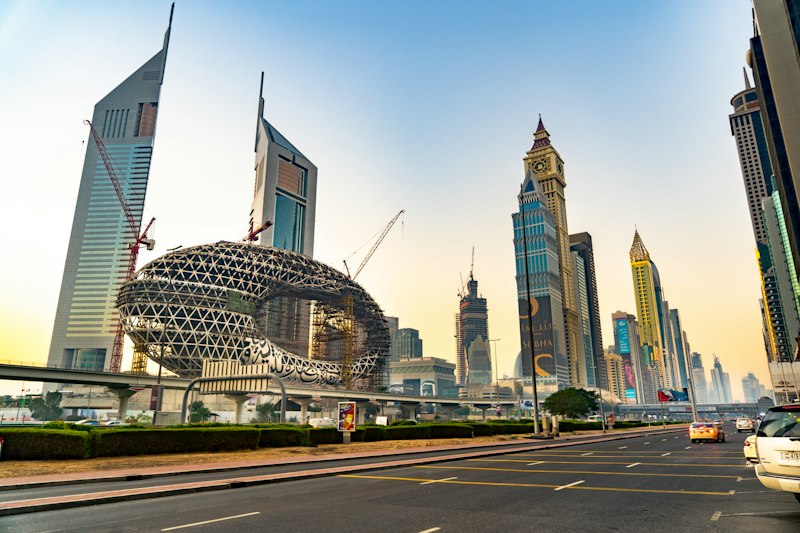
Three Global Cities, Three Different Propositions
Dubai, London, and Singapore are three of the world's most popular destinations for international property investment. Each offers distinct advantages, and the right choice depends on your investment objectives, tax situation, risk tolerance, and time horizon.
At ATAM Properties, we are Dubai specialists, so we naturally believe in the Dubai proposition. But we also believe in honest comparisons. Here is a balanced, data-driven analysis of all three markets.
Entry Costs Compared
The cost of getting into the market varies dramatically:
Dubai
- Average 1-bed apartment price: AED 1,200,000 (USD 327,000 / GBP 258,000)
- Transaction costs: ~7% (4% DLD fee + 2% agency + admin)
- Minimum investment for a studio: From AED 350,000 (USD 95,000)
- Off-plan availability: Yes, with 10-20% deposit and payment plans
- Foreign buyer restrictions: None in freehold areas
London
- Average 1-bed apartment price: GBP 500,000-600,000 (USD 630,000-755,000)
- Transaction costs: ~8-15% (Stamp Duty up to 12% for non-residents + legal fees)
- Minimum investment: GBP 250,000+ (outside Zone 1)
- Foreign buyer surcharge: 2% additional Stamp Duty for overseas buyers (since April 2021)
- Foreign buyer restrictions: None, but significantly higher tax burden
Singapore
- Average 1-bed apartment price: SGD 1,200,000-1,800,000 (USD 900,000-1,350,000)
- Transaction costs: ~30-35% for foreigners (20% Additional Buyer's Stamp Duty + 3% BSD)
- Foreign buyer surcharge: 60% ABSD for foreign buyers (increased from 30% in 2023)
- Foreign buyer restrictions: Cannot buy landed property (HDB) without approval
Winner on entry costs: Dubai. It is not even close. The combination of lower property prices, modest transaction fees, and zero foreign buyer surcharge makes Dubai by far the most accessible of the three markets. Singapore's 60% ABSD has effectively priced out most foreign investors from the residential market.
Rental Yields Compared
| Metric | Dubai | London | Singapore |
|---|---|---|---|
| Gross Rental Yield | 5-8% | 3-4.5% | 3-4% |
| Income Tax on Rent | 0% | 20-45% | 0-22% (residents) |
| Net Yield (after tax) | 4-6.5% | 1.5-3% | 2.5-3.5% |
| Annual Property Tax | None | Council Tax | Property Tax (10-20%) |
Winner on rental yield: Dubai. The tax-free advantage is decisive. A London landlord earning GBP 30,000 in annual rent might keep only GBP 18,000 after income tax. A Dubai landlord earning the same amount (AED equivalent) keeps the full amount.
Capital Appreciation
Dubai
Dubai has delivered strong capital appreciation in recent years (10-20% annually in popular areas from 2021-2025). However, the market experienced a significant correction from 2014-2020, with prices dropping 25-35% from peak to trough in some areas. The current price levels in many areas are still below or around the 2014 peak in real terms, suggesting room for growth.
London
London has historically delivered steady, long-term capital appreciation averaging 5-7% annually over 20+ year periods. The market is deep, liquid, and has centuries of track record. Prime Central London (PCL) properties in Mayfair, Knightsbridge, and Chelsea are considered among the safest real estate assets globally. However, recent years have seen muted growth, and the post-Brexit environment has introduced new uncertainties.
Singapore
Singapore's property market is tightly regulated by the government, which intervenes to prevent overheating. This creates stability but limits upside. Private residential prices have risen steadily (3-5% annually), but the high ABSD means foreign investors need substantial appreciation just to break even on transaction costs. Singapore property is more about preservation than growth for foreign buyers.
Winner on capital appreciation: It depends on your timeline. London for 20+ year wealth preservation. Dubai for 5-10 year growth potential. Singapore for stability but limited upside.
Tax Environment
This is where Dubai's advantage is most dramatic:
| Tax Type | Dubai | London | Singapore |
|---|---|---|---|
| Income Tax on Rent | 0% | 20-45% | 0-22% |
| Capital Gains Tax | 0% | 18-28% | 0% (SSD applies) |
| Annual Property Tax | 0% | Council Tax | Property Tax |
| Inheritance Tax | 0% | 40% | 0% |
| VAT on Residential | 0% | 0% (exempt) | 9% GST (new property) |
Winner on tax: Dubai by a wide margin. Zero across every category. For a UK-based investor, the inheritance tax alone can be a compelling reason to consider Dubai — a GBP 1 million London property could trigger a GBP 400,000 inheritance tax liability, while a Dubai property passes to heirs with zero tax.
Visa and Residency Benefits
- Dubai: AED 2M investment = 10-year Golden Visa for the entire family. No minimum stay requirement.
- London: No property-linked visa. The Investor Visa (Tier 1) was closed in 2022. Property ownership alone does not grant any residency rights.
- Singapore: No property-linked visa. The Global Investor Programme requires SGD 10M+ investment in a business, not property.
Winner on visa benefits: Dubai, decisively. The Golden Visa programme is one of the most generous property-linked residency schemes globally.
Currency and Economic Stability
- Dubai (AED): Pegged to USD at 3.6725. Provides dollar stability but no independent monetary policy.
- London (GBP): Free-floating currency with deep liquidity. Subject to political and economic fluctuations (Brexit impact was significant).
- Singapore (SGD): Managed float by the Monetary Authority of Singapore. Consistently strong and stable, often considered a safe-haven currency.
Winner on currency stability: Singapore, followed by Dubai's dollar peg providing predictability.
Market Maturity and Liquidity
- London: Centuries of property market history, deep liquidity, transparent pricing. You can sell a London property quickly at a fair price in almost any market condition.
- Singapore: Well-established market with strong government oversight. Good liquidity for well-located condos.
- Dubai: A younger market (freehold from 2002) with less historical data. Liquidity is good in prime areas but can be thin in secondary locations. The market is maturing rapidly but is not yet at London's level.
Winner on maturity: London, with Singapore a close second.
The Verdict: Which Market Suits You?
- Choose Dubai if: You want the highest net rental income, tax-free returns, a residency visa, and you are comfortable with a dynamic, younger market. Best for income-focused investors with a 5-10 year horizon.
- Choose London if: You want a ultra-safe, proven market with deep liquidity and you are less concerned about rental yield. Best for wealth preservation and very long-term holding (generational wealth).
- Choose Singapore if: You are already a Singapore resident or citizen (to avoid the 60% ABSD). For foreign investors, the entry costs make it very difficult to justify purely on financial returns.
Want to Explore the Dubai Advantage?
While each market has its merits, Dubai offers an unmatched combination of high yields, zero taxes, visa benefits, and accessible entry costs that few global cities can match. At ATAM Properties, we help international investors — including many who already own property in London or Singapore — build Dubai portfolios that complement their global real estate holdings. Contact our international investment team for a personalised comparison based on your specific circumstances, tax residency, and investment goals.
ATAM Properties
Real estate expert with extensive knowledge of Dubai's property market.
